Retirement blues
Loading article...
-
 Photo - Monkey Business Images
-
Photo - Monkey Business Images
-
 Photo - Monkey Business Images
-
 Contributed
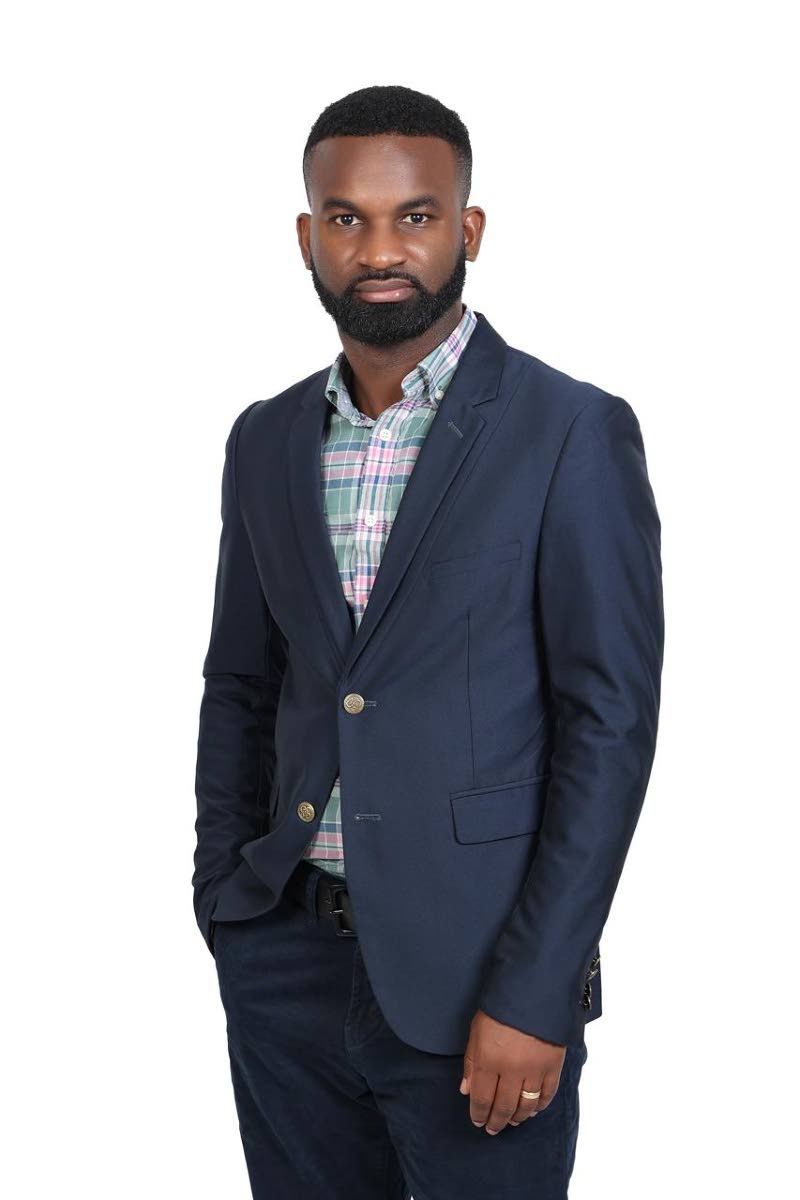
Ken O’Connor, member of the PIAJ’s Public Education Committee. Photo - Contributed
With private pension coverage standing at just 12.08 per cent of Jamaica’s employed labour force, the Pension Industry Association of Jamaica (PIAJ) is urging workers across generations to take a more deliberate approach to retirement planning.
Jamaica has approximately 1.44 million people in its employed labour force, but active private pension coverage stood at only 12.08 per cent as at September 2025, raising concerns about how adequately workers are preparing for life after employment.
The figures suggest that many Jamaicans may be approaching retirement without formal long-term savings arrangements, potentially leaving them dependent on personal savings, family support, real estate, business interests or the National Insurance Scheme (NIS).
Ken O’Connor, a member of the PIAJ’s Public Education Committee, said the low participation rate highlights a significant retirement savings gap and reinforces the need for greater awareness and participation in retirement planning.
“The relatively low level of private pension participation suggests that a significant portion of the workforce is not preparing for retirement through formal retirement savings arrangements,” O’Connor said.
For many workers, retirement planning is overshadowed by immediate financial obligations, including housing, education, raising children and meeting everyday expenses. Younger employees, in particular, may regard retirement as a concern for another stage of life.
“Many people underestimate both the cost of retirement and the benefits of starting early, which results in retirement planning being postponed until retirement begins to feel more immediate,” he said.
Longer life expectancy
However, the traditional notion of retirement as a complete departure from employment at age 60 or 65 is changing. With longer life expectancy and evolving employment patterns, many Jamaicans are choosing to remain economically active beyond the traditional retirement age.
O’Connor said retirement was increasingly becoming less about stopping work entirely and more about transitioning into another phase of life that could include consulting, entrepreneurship, part-time employment or voluntary service.
The changing nature of retirement also means financial preparation must be tailored to different generations.
For baby boomers, who are already retiring or approaching retirement, the priority is determining whether their savings and investments can sustain them throughout their post-employment years.
O’Connor recommends assessing expected retirement expenses, pension income, personal savings, investments, insurance coverage, debt obligations and anticipated healthcare costs.
“Baby boomers should begin by taking a comprehensive inventory of their expected retirement expenses, pension income, personal savings, investments, insurance coverage, debt obligations, and anticipated healthcare costs,” he said.
Seeking professional financial advice may also help retirees identify potential shortfalls and manage their resources effectively.
Generation X, he said, is entering a critical stage of retirement preparation, often while balancing mortgages, children’s education and responsibilities towards ageing parents.
O’Connor recommends maximising pension contributions where possible, reducing high-interest debt, reviewing investment allocations and developing a clear retirement income strategy.
“Generation X is at a critical stage in the retirement planning journey,” he said.
Identifying gaps now provides an opportunity to make adjustments before retirement begins. His advice to this generation is to “close the gap” while there is still time to strengthen their financial position.
Millennials, meanwhile, are navigating an increasingly flexible employment landscape, with many moving between employers, working on contracts, freelancing or becoming entrepreneurs.
O’Connor said retirement planning must remain a priority regardless of employment status. Consistent saving, disciplined investing and maintaining retirement contributions through career transitions are essential.
Build retirement security
He also pointed to Approved Retirement Schemes in Jamaica, which provide options for individuals outside traditional employment arrangements to join, contribute and build retirement security.
“Regular saving and investing over time can have a tremendous impact on future financial security,” he said.
For Generation Z, retirement may appear far removed from current financial priorities. However, O’Connor believes young workers possess an important advantage: time.
Starting early allows savings to benefit from compound growth, whereby investment earnings generate additional earnings over time. Even relatively small contributions made consistently can accumulate significantly over several decades.
“The difference can be substantial,” O’Connor said, explaining that individuals who begin saving in their 20s can accumulate considerably more than those who start later.
His message to Generation Z is: “Start now. Time is your greatest financial asset, and the earlier you begin, the greater the benefits of compounding.”
Although participating in a pension plan is an important step, O’Connor cautioned that having a pension does not automatically mean an individual is adequately prepared for retirement.
Readiness depends on contribution levels, years of participation, investment performance, inflation, healthcare costs, life expectancy and other financial resources. He encouraged Jamaicans to assess whether their projected retirement income will be sufficient to maintain their desired standard of living.
Other investment opportunities, including the stock market, mutual funds, small businesses and real estate, may also help generate income.
Starting
too late
O’Connor identified several common retirement-planning mistakes, including starting too late, contributing too little, underestimating healthcare costs and relying heavily on family support.
He also warned against spending pension refunds whenever workers change jobs, advising them to leave the money invested until retirement or secure deferred annuities when exiting pension plans.
For those participating in group pension plans, he recommended making maximum voluntary contributions where possible. Individuals in retirement schemes should also consider contributing up to the maximum 20 per cent of their earnings.
Balancing retirement savings with immediate financial responsibilities requires careful budgeting. O’Connor said retirement should be treated as an essential financial priority rather than something that can be indefinitely postponed.
“Achieving balance requires thoughtful budgeting and disciplined financial planning,” he said.
Employers also have a role to play in encouraging retirement preparedness. Beyond providing pension plans, they should educate workers about the benefits of early and consistent contributions and encourage participation from the beginning of employment.
With more Jamaicans working outside traditional permanent employment, O’Connor said retirement savings solutions must continue evolving through greater accessibility, flexible contribution structures, simplified enrolment and targeted financial education.
Approved Retirement Schemes already provide options for contract workers, entrepreneurs and self-employed individuals, but greater collaboration among employers, policymakers, financial institutions and industry stakeholders is needed.
The PIAJ is also seeking to deepen its understanding of Jamaicans’ retirement preparedness through its first national survey on the subject.
O’Connor said the survey is expected to provide insight into financial behaviours, retirement expectations, confidence levels and barriers to saving. Its findings should help inform public education initiatives, industry strategies and policy discussions aimed at improving retirement readiness across Jamaica.
With private pension participation remaining low, the challenge is to encourage more Jamaicans to treat retirement not as a distant event, but as a financial goal that requires action today.
editorial@gleanerjm.com